In 2024, across the states with HealthCare.gov, about 8.8 million of the 46 million in-network claims that were in ineligible cases were denied, according to data from the Affordable Care Act Marketplace insurers analyzed by Moneygeek.
Health insurance is supposed to protect you from big medical bills, but things can get messy when your claim gets denied or the payment drags on forever. If you want to make sure you actually get the coverage you’re paying for, you need to know how these disputes play out.
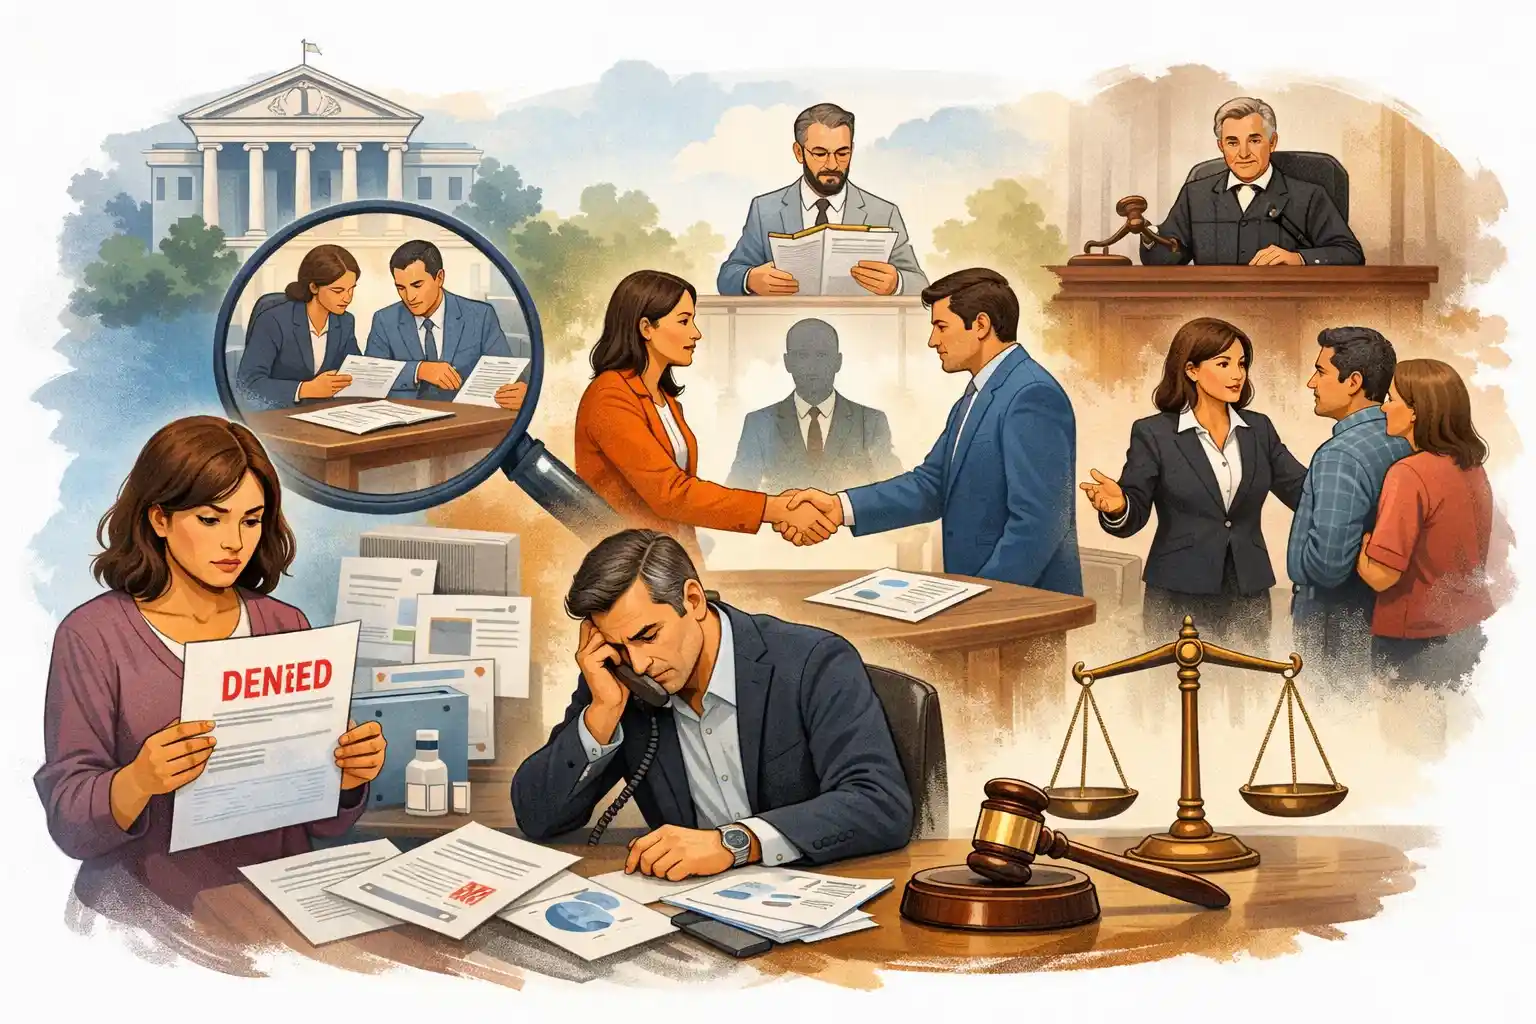
Commonly, it starts with the insurance company doing their own review. They look over your paperwork and whatever proof you have. If that doesn’t sort things out, health insurance lawyers can give you advice, or you can take it up with a government agency for an outside appeal.
Let’s explore the key steps and considerations for managing health insurance claim disputes effectively.
Understanding the Denial of Claims
Receiving a rejection of a claim for health insurance can often mean a frustrating and demoralizing experience, particularly when you think that some specialized services you needed should have been included in your coverage.
It has to be understood that there are different rationales for health insurance companies to turn down the claims; it could be a function of coding errors or missing pieces of information on your health claim. Your plan may not cover certain procedures or services included in your policy.
If you are having such concerns, perhaps asking those who experienced the same hurdle can give you direction.
The Appeals Process Explained
Do you think your claim denial was wrong? There are ways to make an appeal so you can receive the coverage you deserve.
You may write an appeal to your insurance coverage, pointing out the numerous reasons why that denial was wrong in terms of eligibility. Be certain that all of your explanations include the requisite supportive documentation, like medical records or bills.
Be mindful of the hard window of time within which you must submit an appeal, as it can be tight. Upon receiving the appeal, the insurer should review your case and reply within a particular time span. You may require an independent external reviewer for appeal if they uphold the denial.
Effective Communication With Your Insurer
If your claim was denied, you can still make appeals. According to https://www.shaverlegal.com/, policyholders have the right to expect their insurance provider to act in good faith by paying out their claim.
Negotiating the various stages of the appeal process can be quite intimidating, but good communication with your insurer is likely to make the difference in how the appeal goes.
Collate all the important documents and facts about the case. Communicate briefly but thoroughly when you reach out. Use a friendly yet assertive-sounding voice. Convey what your concerns are and that you are seeking to come to an agreement. Be sure too to ask questions when something is not clear.
Keeping a record of conversations with written notes will be useful in keeping you updated and organized. With patience and persistence, follow up on your requests: sometimes you don’t get answers until the third phone call.
Exploring Mediation Options
While conflict resolution for insurance claims could seem unmanageable, options for mediation are an alternative that is beneficial for both parties.
During the mediation process, parties are at liberty to air their biases in strict accordance with set regulations in case they request assistance in ironing out mutual differences from a neutral administrator. An exploration of differences in the benign and favorable verbal exchange would detract from the adversarial dispute approach both parties wish to retain for a more formal legal clash.
Both sides will be as open and honest as they sincerely want. Your goal should not be to completely overwhelm the insurer. The most intense feelings may lessen if both parties maintain control of the process and conversation, allowing each other the necessary time to either signal a rejection or reach an agreement. This humanitarian stance shows respect for your dignity and courtesy in your relationship with your insurer.
When to Consider Legal Action
There are instances when cases involving health insurance claims can be appropriately mediated, although that mediation will not always lead to satisfactory resolution. Should the mediation proceedings reveal the insurance provider’s intransigence, you may consider filing a lawsuit. If you feel the insurer has harmed you or if this denied appeal has negatively impacted your well-being with respect to your health, then litigation is an obvious course.
Weigh your advantages and disadvantages before actually entering into actual litigation. It’s best to have a deep discussion with a lawyer first to help clarify matters and point out your rights.
Don’t feel disheartened, as there are others who are facing the same problems. You can seek help from these communities so you can feel supported.